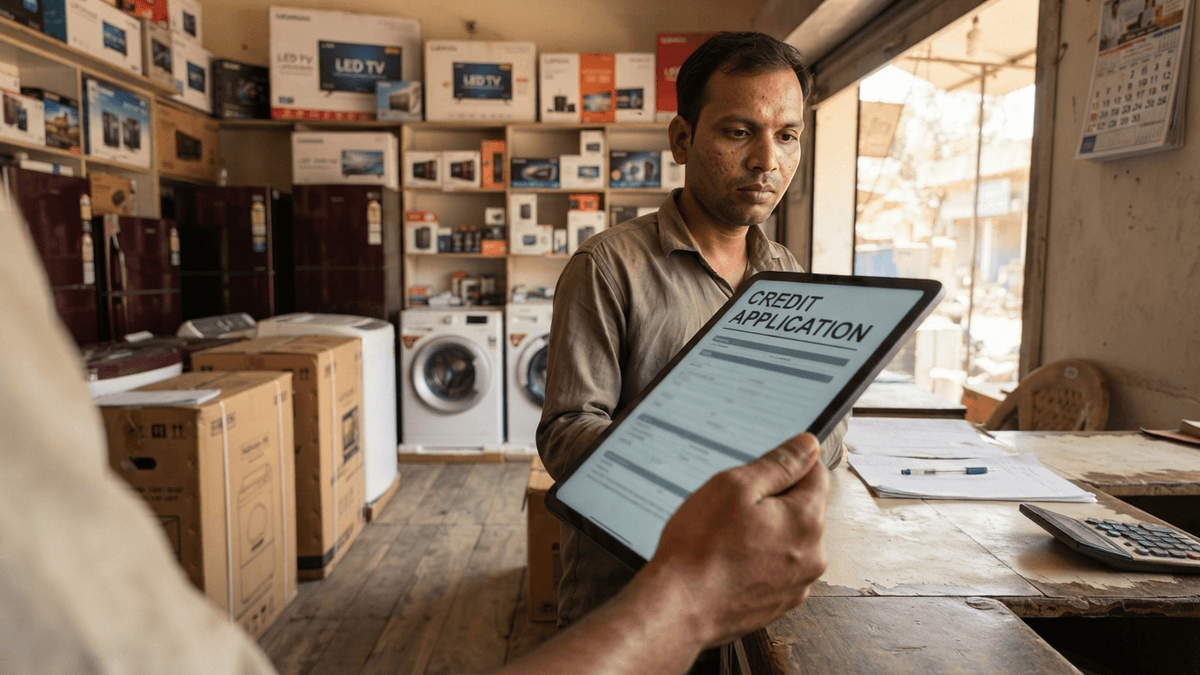
A customer applies for a consumer durable loan in a semi-urban Indian electronics shop.
Institutional credit access in India has experienced a significant expansion, with the share of eligible borrowers participating in formal financial systems rising from 35% in 2017 to 74% as of March 2024. This trend underscores a structural shift in the Indian retail credit landscape, moving beyond traditional urban centers into smaller, semi-urban, and rural geographies.
Data indicates that consumer durable loans are acting as a primary entry point for new-to-credit customers, facilitating their transition into the formal banking sector. Additionally, microfinance institutions and gold-backed lending products continue to play critical roles in bridging the credit gap for unbanked and underbanked populations.
For institutional investors and private equity firms, this data suggests a broadening addressable market for financial services providers. The sustained year-on-year growth in retail credit portfolios points to increased financial inclusion, which serves as a catalyst for deeper market penetration by NBFCs and fintech platforms. As these first-time borrowers establish credit histories, they represent a growing pipeline for higher-value financial products, signaling long-term growth opportunities in India’s consumer finance sector.
About the Author