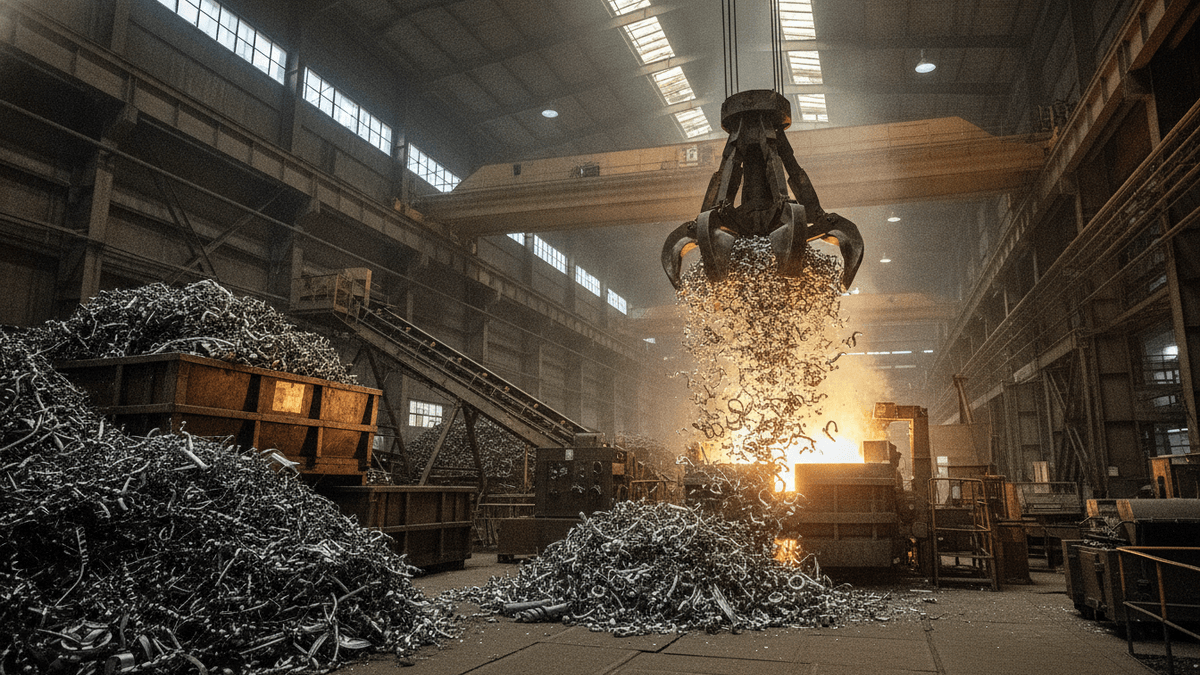
Steel turnings and chips loaded into an electric arc furnace facility
The global market for steel industrial turnings and chips is set for significant expansion, projecting a volume compound annual growth rate (CAGR) of 3.0–4.5% from 2026 to 2035. This upward trend is largely propelled by the growing reliance on electric arc furnace (EAF) steelmaking processes, which utilize ferrous scrap as a key input to reduce carbon emissions.
Asia-Pacific currently leads both the supply and consumption of steel turnings and chips, with substantial contributions stemming from machining activities in China, India, and Japan. Europe and North America are also key players, demonstrating a strong demand for low-copper turnings essential for specialty steel applications.
The market landscape is evolving with the emergence of digital platforms for scrap procurement, though it continues to be influenced by price volatility. Primary growth drivers include global decarbonization initiatives, expansion in manufacturing sectors, and the implementation of circular economy policies. However, challenges such as inconsistent material quality and logistical complexities persist.
Key end-use sectors for steel turnings and chips encompass EAF steelmaking, foundries, industrial machinery manufacturing, the automotive industry, and electronics production. By 2035, the market is expected to reach an index of approximately 145, indicating substantial market development.
About the Author