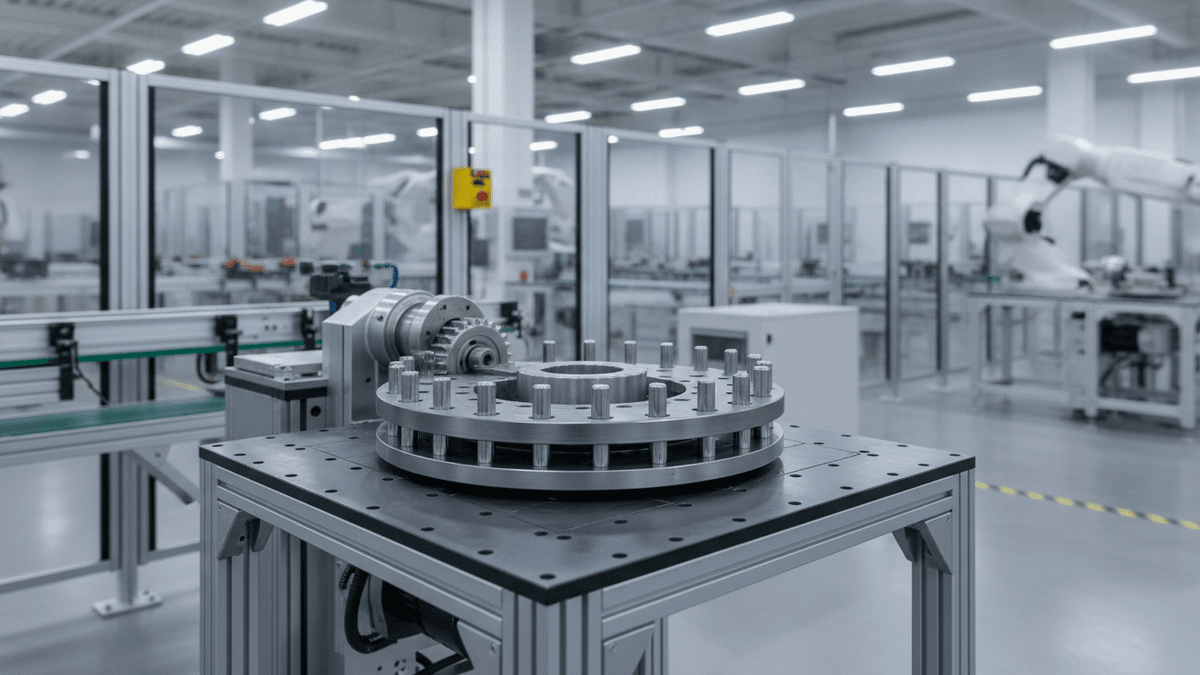
Pin Gear Drive Unit in an automated manufacturing facility.
The global Pin Gear Drive Unit Market is set for substantial expansion, with projections indicating a rise from USD 680.6 million in 2026 to USD 1301.8 million by 2036, reflecting a Compound Annual Growth Rate (CAGR) of 6.7%. This growth trajectory is underpinned by the increasing demand for repeatable, low-backlash motion solutions essential for compact automated machinery across various industries.
Key market segments highlight specific areas of demand. Cam pin gear drives are expected to capture a significant 27.0% market share in 2026, owing to their reliable backlash-controlled rolling contact. Medium torque units are forecast to hold 39.0% of the market in the same year, driven by their utility in common indexing tasks. The high-precision units segment is projected to lead, accounting for 46.0% of the market share in 2026, as automated axes increasingly require precise bidirectional positioning capabilities.
Applications for these drive units are diverse, spanning indexing tables, robotics, packaging machinery, machine tools, and material handling systems. Indexing tables, in particular, are anticipated to represent 28.0% of the application market in 2026, a demand fueled by their frequent use in assembly processes. From a sales channel perspective, direct OEM purchasing is expected to dominate, securing a 48.0% market share in 2026. This preference is attributed to the necessity for coordinated sizing and the mitigation of interface risks during the machinery design and integration phases.
While growth opportunities are evident, the market faces certain restraints. Improper mounting practices can lead to reduced repeatability and accelerated wear, potentially slowing adoption. Challenges related to rack alignment and preload, often exacerbated by divided commissioning responsibilities, can also compromise overall axis accuracy. However, the availability of matched drive packages presents a significant opportunity by streamlining engineering cycles through documented components and coordinated local installation support.
Regionally, South Korea is projected to exhibit the highest CAGR at 6.5% through 2036, driven by concentrated investment in machinery and robust integrator networks. Other key markets include the United States (5.8% CAGR), Germany (5.4% CAGR), Japan (5.1% CAGR), and Italy (6.2% CAGR).
Major players in this competitive landscape include Tsubaki, Nexen Group, Kamo Seiko, GAM Enterprises, WITTENSTEIN alpha, APEX Dynamics, STOBER, and ATLANTA Drive Systems. These companies differentiate themselves through distinct architectural approaches, regional engineering support, and specialized product offerings. Recent strategic moves include Tsubaki’s showcase of its pin gear drive units at Smart Factory plus Automation World in Seoul in March 2025 and APEX Dynamics’ participation in the China International Industry Fair in August 2025. GAM Enterprises’ agreement to acquire selected Schaeffler Ultra Precision Drives assets in April 2026 and STOBER’s introduction of its next-generation KS servo gearbox in March 2026 also mark significant developments in the sector.
About the Author