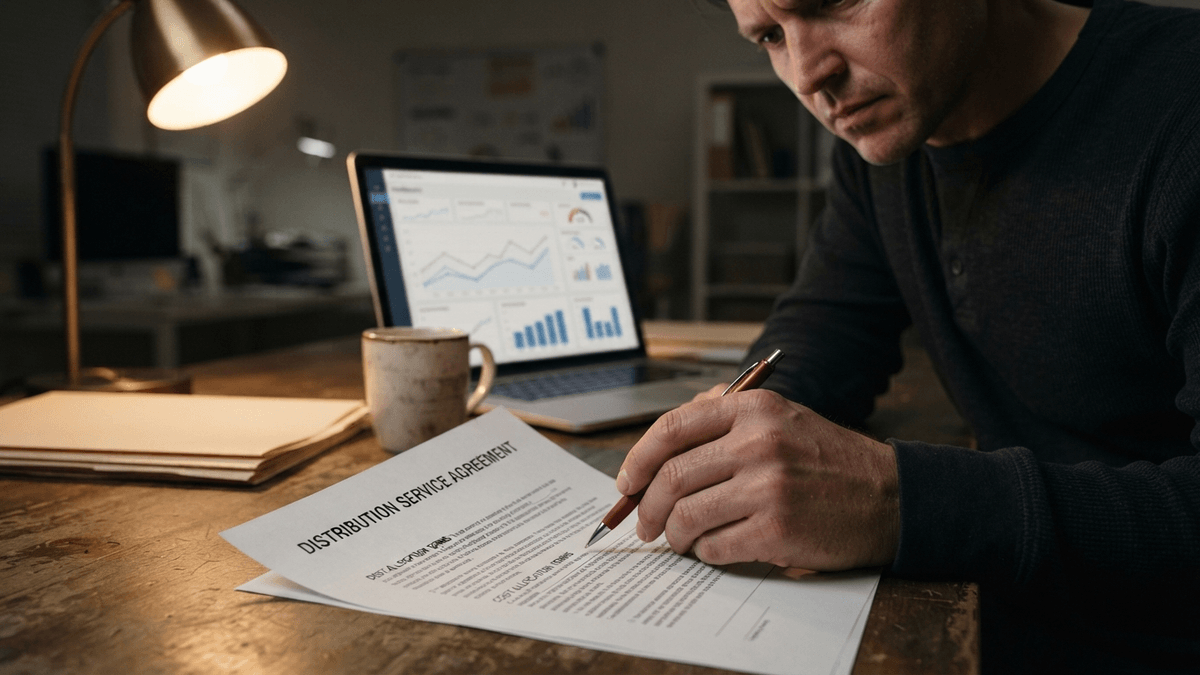
A distributor reviews a service agreement amid rising cost pressures.
The industrial distribution sector is facing a critical inflection point as manufacturers, buoyed by optimistic growth forecasts, increasingly shift operational cost burdens onto their supply chain partners. For private equity firms and institutional investors overseeing portfolio companies in the distribution space, this trend signals a period of heightened margin sensitivity and a necessary shift in capital allocation strategies.
According to analysis from Distribution Strategy Group, the current environment is forcing distributors to move beyond traditional service models. As manufacturers offload overhead costs to preserve their own profitability, distributors are finding that legacy pricing structures no longer suffice. For investors, this creates an urgent mandate to audit the operational efficiency of portfolio assets and push for more sophisticated, data-driven pricing models.
The strategic implication is clear: the ability to maintain profitability in this climate requires a more rigorous approach to manufacturer-distributor contract renegotiations. Firms that fail to optimize their supply chain relationships or improve internal operational margins risk significant valuation compression. Moving forward, market participants should expect increased M&A activity focused on distributors that have successfully implemented automation and advanced analytics to navigate these inflationary pressures.
About the Author