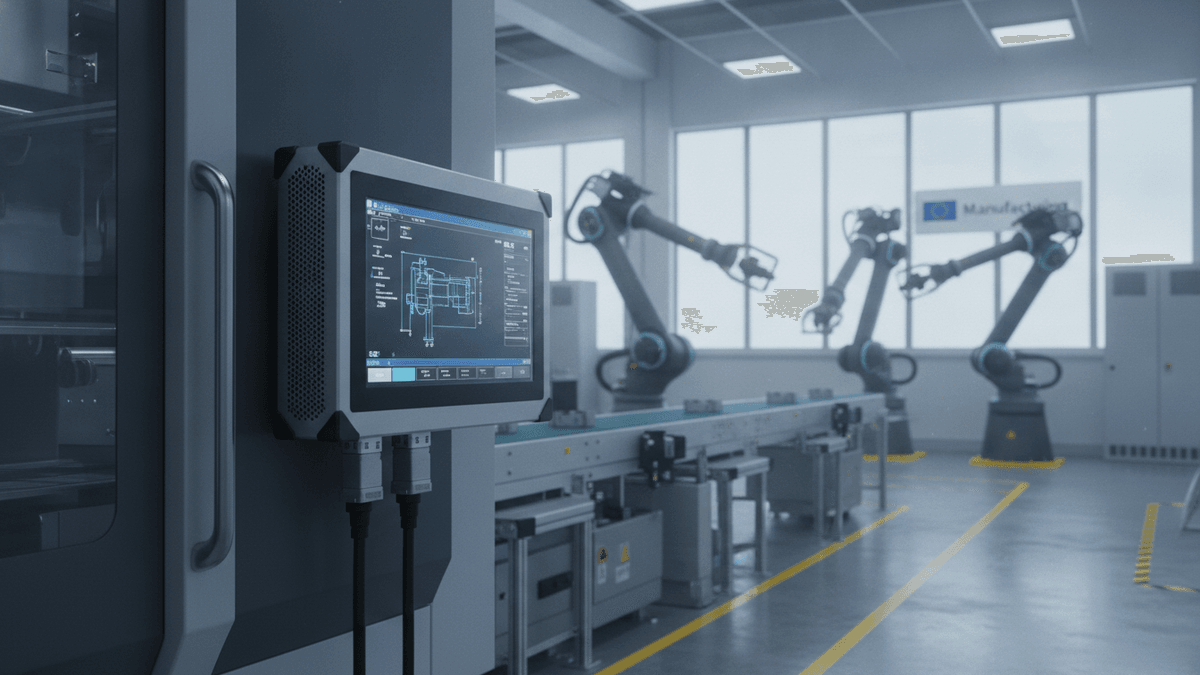
Industrial PC integrated into factory machinery on a modern European factory floor
The European Union’s Industrial PC (IPC) market is anticipating robust growth, with projections indicating a compound annual growth rate (CAGR) of 5-7% between 2026 and 2035. This expansion is primarily fueled by the escalating adoption of factory automation, the ongoing energy transition, and the critical need to replace aging legacy systems across the continent.
Demand is particularly strong for Panel PCs and Box PCs. A notable trend within the market is the increasing preference for ruggedized and fanless designs, reflecting a requirement for enhanced durability and reliability in demanding industrial environments. Currently, the market exhibits a significant dependency on imports, with a substantial portion of IPCs sourced from Asia. This reliance exposes the sector to vulnerabilities such as supply chain fragility, complex regulatory landscapes, and intense price competition.
Key market trends point towards a strategic shift to more modular and scalable platforms. These advanced solutions are designed to effectively support emerging technologies like edge computing and predictive maintenance, enabling more efficient and data-driven industrial operations. Geographically, Germany, Austria, and Northern Italy are identified as the primary centers of demand for Industrial PCs within the EU.
The market’s trajectory is significantly shaped by a stringent regulatory framework. Compliance with standards such as CE marking, ATEX, RoHS, WEEE, and the recently introduced Cyber Resilience Act is paramount. These regulations are not only compliance hurdles but are also creating substantial opportunities for manufacturers that can deliver secure, sustainable, and application-specific IPC solutions tailored to the evolving needs of European industries.
About the Author