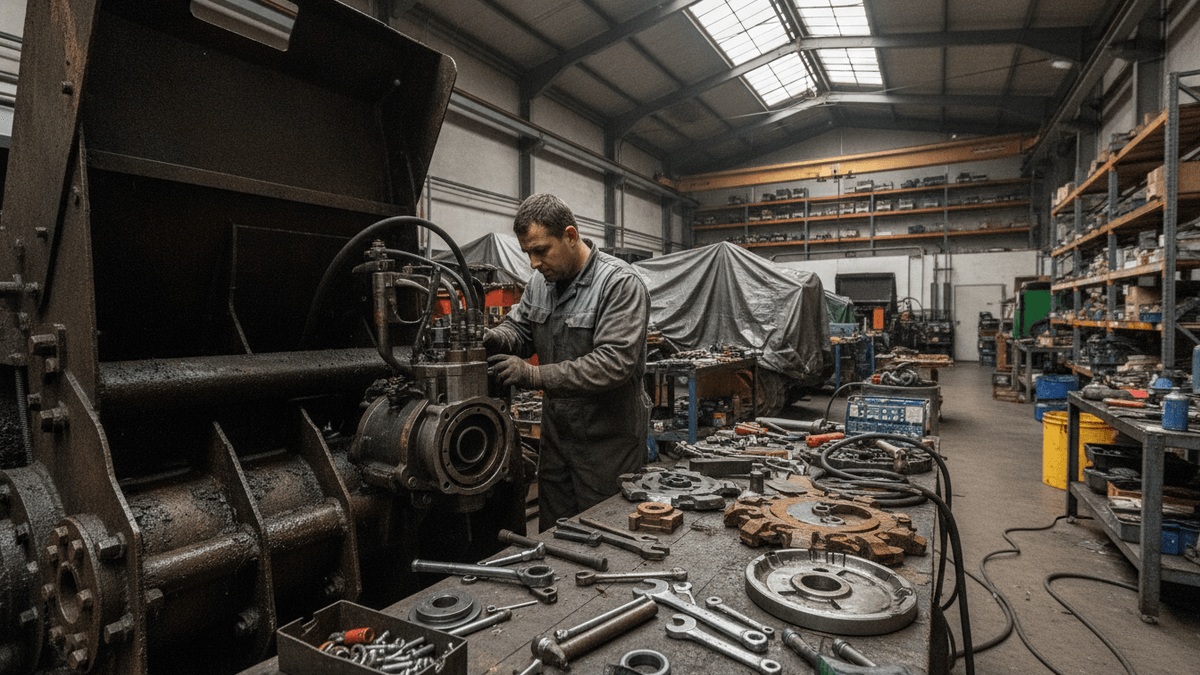
Mechanic inspects heavy-duty industrial mulcher in a workshop
Alamo Group (ALG) stock experienced an approximate 4% rally, even as the company continues to face persistent margin compression. For the second quarter, Alamo Group reported revenues of US$450.7 million, marking a 7.6% increase compared to the previous year, with basic earnings per share reaching US$2.56. Despite these solid top-line figures, the trailing net margin has thinned to 6.1% from 7.4% a year ago, indicating a squeeze on profitability.
Proponents of Alamo Group suggest that the company is strategically moving towards a higher-margin, higher-quality earnings profile through operational enhancements and acquisitions. The Q2 revenue growth is consistent with this narrative, supported by strength in Industrial Equipment and contributions from recent acquisitions like Petersen Industries and Ring O Matic. However, the persistent decline in net margin and a slight dip in basic EPS from US$2.59 to US$2.56 raise questions about whether the promised operational leverage is effectively translating to the bottom line.
Conversely, critics express concerns that factors such as softness in Vegetation Management, a strong focus on acquisitions, and recent leadership transitions could constrain margins and introduce execution risks. The observed 6.1% trailing net margin, down from 7.4%, supports worries that weaker demand in forestry and dealer segments might be impacting overall profitability. The fact that net income, excluding extra items, remained broadly flat at US$30.9 million despite higher revenue, further suggests that increased costs, product mix, or pricing pressures are offsetting volume gains. The slight decrease in EPS also indicates that earnings per share are not keeping pace with revenue growth, lending credence to concerns about integration challenges and capital allocation discipline within Alamo Group.
About the Author