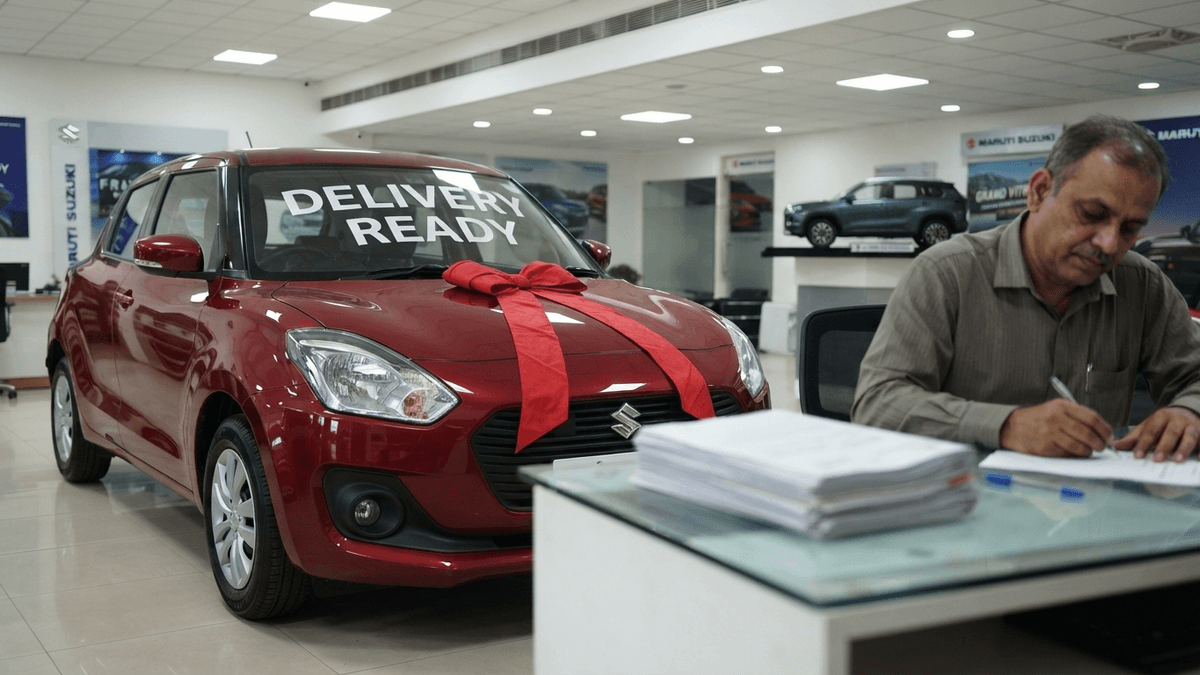
A customer prepares to take delivery of a new hatchback at a Maruti Suzuki dealership.
Recent adjustments to the Goods and Services Tax (GST) have provided a tactical lift to India’s entry-level hatchback segment, signaling a potential stabilization for small-car manufacturers. Data indicates that the market share for these vehicles has risen from 2.3% to 3.3%, a notable recovery for a category that had faced persistent headwinds due to rising input costs and shifting consumer preferences.
Maruti Suzuki, the primary beneficiary of this trend, reported an uptick in demand following the tax rationalization. For institutional investors, this shift highlights the elasticity of the entry-level market, where fiscal policy interventions remain a critical lever for driving volume. However, the broader trend line remains firmly anchored in the sport utility vehicle (SUV) segment, which currently commands a 58% share of the domestic market.
The divergence between the resurgence of hatchbacks and the continued hegemony of SUVs underscores a complex consumer landscape. While lower tax burdens have improved affordability for price-sensitive buyers, the long-term trend reflects a persistent aspiration toward larger form factors. For private equity firms and automotive analysts, the data suggests that while policy intervention can successfully stimulate specific segments, it is unlikely to reverse the structural shift toward premiumization and SUV dominance in the Indian automotive sector.
About the Author